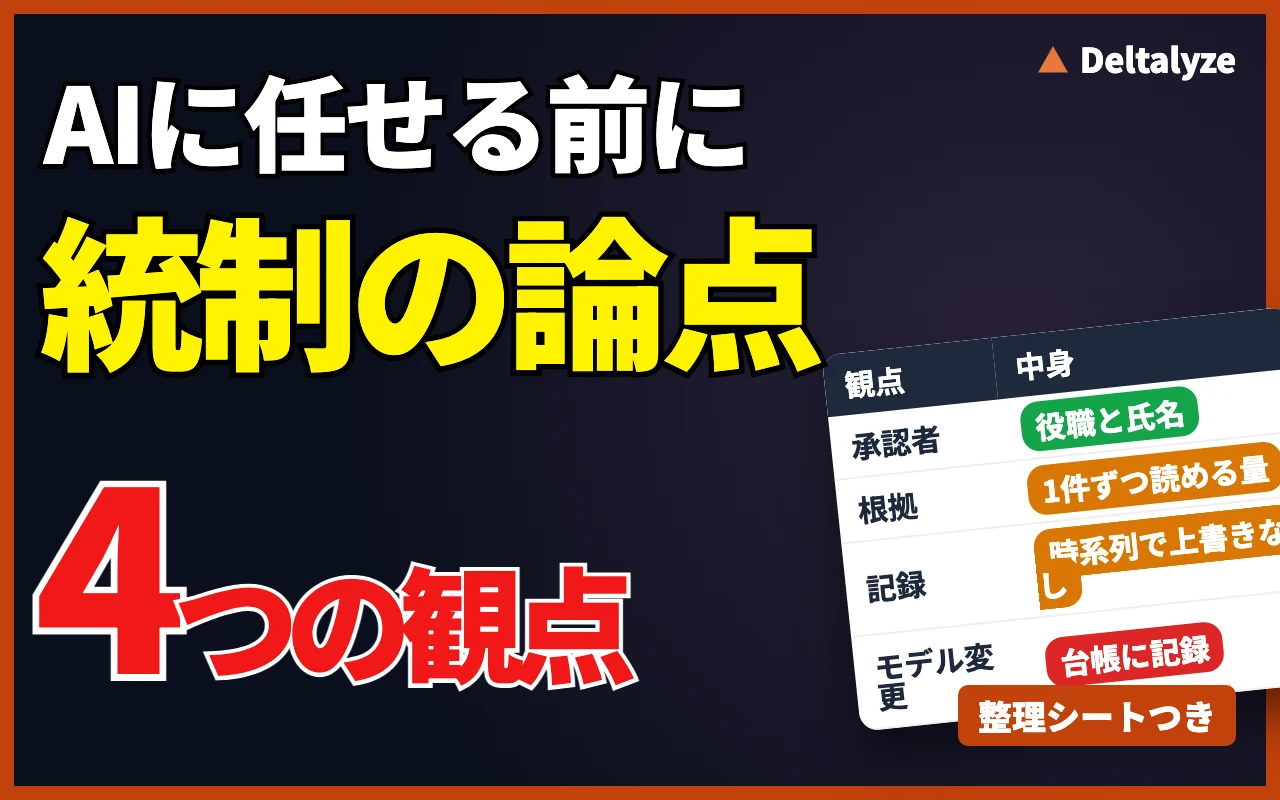
01The operating team does not make this call
Internal control is evaluated on both design and operation. The question is not only whether transactions are processed correctly, but whether the mechanism was designed appropriately and is operating as intended. That assessment sits with the audit firm or internal audit function; it is not something an operating team can conclude on its own.
For that reason, satisfying the points below does not establish that a given design is acceptable. They are simply the areas most often examined. What is actually permitted depends on your overall control environment and on your auditors' judgment.
The value of settling these points early shows up in what the actual deficiencies look like. Tokyo Shoko Research's survey of disclosed internal control deficiencies among all listed Japanese companies for FY2025 (published 14 May 2026) counted 41 companies and 42 cases. Fifteen of those 41 named a shortage of staff, or insufficient knowledge among the people assigned, as a cause. When a team is already short-handed, the strain tends to surface on the control side first.
02Decide where approval sits
Decide who approves the AI output before operation begins. Starting without a named approver means reconstructing accountability afterwards, which slows the review considerably. A practical rule is to look at who finalised the transaction before AI was involved. The person with authority to post the entry is usually the natural approver for the AI's proposal as well.
Be explicit about what is being approved. Accepting a suggestion as-is and accepting it after correction carry different meanings. Keeping both in the record makes the history traceable. Deleting rejected proposals has the same effect as overwriting, so keep those too.
- Name the approver before go-live, down to role and person
- Distinguish acceptance from acceptance-after-correction
- Keep rejected proposals with a reason
- Keep the fact of approval in the record
03Whether approval happens in substance
A record of approval may still be assessed as not functioning if the approver could not actually examine what they were approving. Check whether the basis for the conclusion is visible to the person signing off.
If an AI proposes an account classification, for example, what the approver can verify differs depending on whether the underlying transaction detail and comparable prior treatments are presented alongside the suggestion.
Adding more approvals does not automatically make the process safer. In a study where 27 radiologists read 50 mammography cases with AI suggestions attached (Dratsch T et al., Radiology, 2 May 2023, DOI 10.1148/radiol.222176), accuracy among the least experienced group fell from 79.7% to 19.8% when the AI suggestion was wrong. Even the most experienced group, averaging 10.8 years, fell from 82.3% to 45.5%. It is a clinical experiment and does not transfer directly to accounting work. Still, the pattern is worth holding in mind when designing approvals: as the number of items to check grows, each individual check gets thinner.
In practice, check whether the volume fits inside the time an approver actually has, with room to open the basis of each item. If it does not, consider varying the depth of review by amount or by supplier, and make that split itself a topic for the auditors.
Whether the information is sufficient is best confirmed with the person who will actually approve. Their read is usually more accurate than what the design assumes. The table below is a quick way to review the approval and record design.
| Check | Acceptable state | Needs rework |
|---|---|---|
| Approver | Role and name fixed before go-live | Only "someone will check" is written |
| Object of approval | As-proposed and after-correction acceptance are recorded separately | Only whether it was accepted is kept |
| Evidence visible to approver | Source transaction and prior treatments appear on the same screen as the proposal | Only the conclusions appear in a list |
| Volume per approver | Each item's basis can be read within the time available | Volume forces bulk approval |
| Records | Input, output and human decision kept in sequence, never overwritten | Only the corrected version is saved |
| Change control | Date and content of model or instruction changes are in a register | Nobody can say when it changed |
04Why controls fail even with an AI policy
An approval step can exist while approvers sign off without reviewing the content. The same pattern appears in AI use. A company may have an AI policy, yet not everyone knows which information must not be entered into AI tools. When the policy is revised, teams lack the time to catch up.
Reactions then split. Some people enter information that should never go into an AI tool. Others avoid AI altogether because they fear the risk. Still others use AI tools the company has not approved, which is known as shadow AI. Each reaction shows that a policy that exists only as a document does not create control.
The strength of controls also needs balance. Controls that are too strict slow the work down and end up being bypassed. A practical approach is to put operational efficiency and improvement first, and add only the minimum controls needed to ensure the accuracy, completeness, and validity that disclosure rules and regulations require.
05Whether it can be reconstructed later
Being able to reconstruct the basis of a decision is a frequent point of examination. Check whether it is possible to follow, in sequence, what data was referenced, what the system produced, and how a person judged it.
If the AI output is overwritten on save, the original suggestion disappears. Holding the before and after separately makes the reasoning far easier to explain. Splitting the record into four parts (input data, AI output, the human decision, and the corrected content with its reason) also makes it easier to walk the auditors through.
Records matter because noticing in the moment is not something to rely on. In a study where over 100 participants worked alongside an AI agent for roughly five hours (Ye J et al., arXiv:2606.05647, 4 June 2026), 94% failed to detect problems the agent had deliberately introduced. Even when given a monitoring tool, 56% ignored its warnings and accepted the output anyway. A record you can trace afterwards is the only handle you have when nobody caught it at the time.
- Hold referenced data, output, and human judgment separately
- Do not overwrite; keep both states
- Record who decided and when
- Make the sequence followable
06Whether behavioural change is visible
AI behaviour can shift when a model is updated or a setting is changed. If the fact and timing of such changes are not recorded, it becomes impossible to explain why results differ from a certain point onward. Rewriting the instructions given to the AI counts as a change too.
Managing these changes usually maps onto existing system change control. Where an internal precedent exists, aligning with it is the faster route. Decide as well how you will compare results before and after a change. Fixing a set of sample items drawn from past processing, and rerunning them whenever something changes, gives the team a routine way to notice a shift in behaviour.
07A worksheet you can copy
This template puts the four points on a single page you can take into the conversation. Any field you cannot fill becomes a question for the auditors. Leaving it blank and asking is faster than filling it with a guess.
Cover one process per sheet. Approvers and record locations differ between processes, and combining them makes the entries vague.
# AI use: control worksheet (for the auditor conversation) ## 1. Target process - Process name: - What the AI does (e.g. proposes only / drafts only): - What the AI does not do: - Rough volume (enter as an example): ## 2. Approval
| Item | Entry |
|---|---|
| Approver (role) | |
| What is approved (as proposed / after correction) | |
| When approval happens | |
| Evidence shown to the approver | |
| How rejections are handled |
## 3. Records
| What to keep | Where | How (never overwrite) |
|---|---|---|
| Input data given to the AI | ||
| AI output (proposal) | ||
| Human decision (accept / correct / reject) | ||
| Corrected content and reason |
## 4. Change control - Model and settings in use: - Where model updates and setting changes are logged: - How results are compared after a change: - Relationship to existing system change control: ## 5. Questions for the auditors - -
08Filled example: invoice account classification
The following is a fictional example. It assumes an AI proposes the account and tax category for incoming supplier invoices, and an accounting supervisor approves before the entry is posted. The volumes and sample sizes only illustrate how to fill the sheet; they are not figures from any real company.
Note that the sheet states what the AI does not do before anything else, and that rejected proposals are kept rather than deleted. Section 5 lists only the points the operating team cannot decide alone.
# AI use: control worksheet (filled example: fictional) ## 1. Target process - Process name: account classification for incoming supplier invoices - What the AI does: proposes the account and tax category, and shows its basis - What the AI does not do: finalise journal entries, approve payment - Rough volume (example): about 200 invoices a month ## 2. Approval
| Item | Entry |
|---|---|
| Approver (role) | Accounting supervisor with authority to post entries |
| What is approved | Both. The screen separates "accept as proposed" from "accept after correction" |
| When approval happens | Before the entry is posted to the ledger |
| Evidence shown to the approver | Invoice line items, the last three treatments for that supplier, the AI's stated reason |
| How rejections are handled | Rejected proposals are kept, with a one-line reason |
## 3. Records
| What to keep | Where | How (never overwrite) |
|---|---|---|
| Input data given to the AI | Invoice image and extracted text | Version as received |
| AI output (proposal) | Classification log | Appended per proposal with timestamp |
| Human decision | Classification log | Approver name and timestamp |
| Corrected content and reason | Classification log | Stored next to the original proposal |
## 4. Change control - Model and settings in use: model name and instruction version number in a register - Where changes are logged: the system change control register - How results are compared: rerun 30 sample invoices from the prior month and check whether proposals changed - Relationship to existing change control: same register, same approval procedure ## 5. Questions for the auditors - Should suppliers with a high correction rate be fixed as 100% review? - Can the classification log follow the same retention period as journal evidence?
09How to bring it to the conversation
With those four points settled, take it to your audit firm or internal audit function. Asking whether AI is permitted tends to stall. Presenting a specific scope, a defined approval point, and a stated record-keeping approach moves the review forward.
The design may well be adjusted as a result. Adjusting before go-live costs far less than being told after the process is running. Where AI adoption stalls on control grounds, the cause is usually not risk. It is that the material needed for a decision was never assembled.
Which areas draw the most scrutiny can be inferred from how disclosed deficiencies break down. In the Tokyo Shoko Research survey cited above, 21 of the 42 cases (50.0%) concerned the closing and financial reporting process, followed by 19 cases (45.2%) of company-level internal control. Deficiencies in business processes accounted for 2 cases (4.8%). If your change touches the closing process, preparing material with that distribution in mind moves the conversation along faster.
You can hand the completed worksheet to an AI to draft the memo. If you do, keep any language that judges control adequacy out of it. If you first need to decide how to carve out the process itself, see how to run a business process inventory and the roadmap for reducing key-person dependency in accounting.
- Narrow it to one process
Write what the AI does and does not do in section 1 of the worksheet.
- Fix the approver and the object of approval
Set role and name, separate as-proposed from after-correction acceptance, and decide how rejections are handled.
- Show the screen to the real approver
Confirm the evidence is sufficient and the volume can be read item by item in the time available.
- Decide where records and change logs live
Choose where input, output and human decisions are kept without overwriting, and the register for model and instruction changes.
- Review with the table and turn blanks into questions
List any item in the needs-rework column, plus every blank field, under questions for the auditors.
- Consult before go-live
Bring the worksheet and memo to the audit firm or internal audit function.
You are assisting a person responsible for internal control in the accounting function of a listed company.
Using the "AI use: control worksheet" below, draft a memo to send to our audit firm or internal audit function.

Requirements:
- In the first three lines, state the target process, what the AI does, and what we want to discuss
- Use three headings: approval, records, change control. Use only what is written in the worksheet
- Do not fill gaps. Mark anything missing as "not entered" and list those items at the end
- Do not use language that judges control adequacy (e.g. "no issue", "appropriate")
- Keep it to roughly one A4 page

Worksheet:
(paste the completed worksheet here)
Read the AI's draft yourself before sending it, and check that nothing outside the worksheet has been added.
KEY TAKEAWAYS
What to carry into implementation
- Internal control is assessed by the audit firm or internal audit function; the operating team's job is to assemble the material
- Name the approver down to role and person, and record as-proposed and after-correction acceptance separately
- Confirm with the real approver that the screen and volume allow each item's basis to be read
- Keep input, output and human judgment in sequence without overwriting, and log model and instruction changes
- Blank fields on the worksheet become your questions for the auditors
FAQ
Frequently asked questions
Does covering these points mean we satisfy internal control?
Not necessarily. The assessment depends on your overall control environment and your auditors' judgment. This piece organises the areas most often examined; it does not determine whether a design is acceptable.
At what stage should we approach our auditors?
Once the design direction is settled and before operation begins. Being able to state the target process, the approval point, and the record-keeping approach makes the review concrete. Raising it after go-live is far more costly to unwind.
Does a person need to review every AI proposal?
How much to review is something to agree with your auditors. If full review is not realistic at your volume, draft a split by amount or supplier and bring that split to the conversation. Avoid reducing review on the operating team's judgment alone.
Do we need records if we only use a chat-based AI to draft something?
If the draft feeds into journal entries or disclosed figures, keeping what was entered, what came out, and who changed what makes it far easier to explain. The scope depends on the process, so list it as a question in section 5 of the worksheet.
Model updates happen on the vendor's side. What should we record?
Record the model name, the version of the instructions you give it, and the date and content of any change you notice. Also fix a procedure that reruns sample items from past processing to compare proposals before and after. Check whether this can sit in your existing system change control register.